Mixed-Use Structural Warranty
Build Secure helps developers, investors and buyers get peace of mind against latent defects in their mixed-use building’s construction.
Get dedicated structural warranties for mixed-use building projects, redevelopments and renovations. Ensure the safety and security of your development.
- Cover available at any stage of the build.
- Fast turnaround times.
- 'A' rated insurers.
- Cover available for any type of build.
- Competitive pricing.
Why choose Build Secure as your mixed-use structural warranty broker?
What isa mixed-use structural warranty?
Mixed-use structural warranties cover properties that are jointly used for both residential and commercial use. Functioning as an extension of a standard commercial warranty, a mixed-use structural warranty protects both residential and commercial units against latent structural defects incurred during the construction or renovation process.
Mixed use-structural warranties can be used by:
- Property developers
- Homeowners
- Self-builders
- Mortgage lenders.
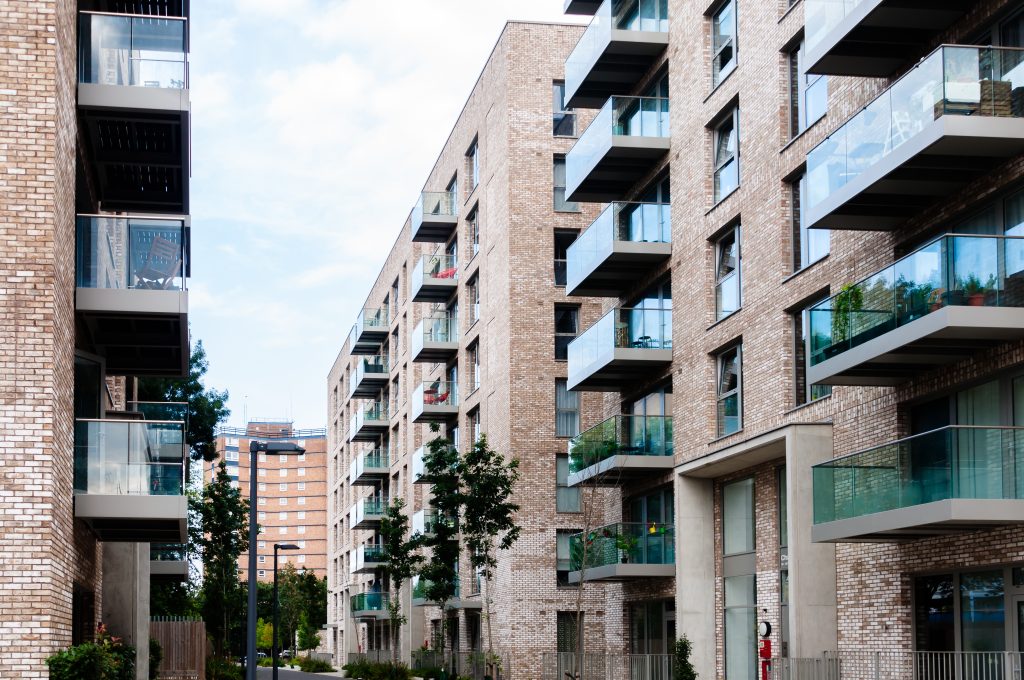
Structural warranties for verticalmixed-use buildings
Developing or renovating a site that includes both residential and commercial units in a single, vertical structure, such as homes above shops or a hospitality and leisure business?
Our vertical mixed-use structural warranties provide a single, unified policy for the whole structure.
We can also support with horizontal mixed-use developments, like retail rows next to townhouses or campuses with dorms. These are usually split or multiple policies, linked by an overarching common site agreement.
Structural warrantiesfor horizontal mixed-use buildings
We can also support with horizontal mixed-use developments, like retail rows next to townhouses or campuses with dorms. These are usually split or multiple policies, linked by an overarching common site agreement.
Work-livevs. work-live-play mixed-use warranties
Thanks to our team’s expert knowledge and close relationships with a range of lending partners, we can provide warranties for mixed-use developments with a range of micro- and macro- risk factors.
We can accommodate simple work-live projects – such as when individual units are designed for joint commercial and residential use. We also cater to large, complex work-live-play schemes, like urban villages, where portfolio arrangements or master mixed-use policies might be required.
Commercial structural warranty FAQs
How are mixed-use structural warranties different from residential or commercial structural warranties?
Mixed-use structural warranties differ from standard commercial or residential policies in their complexity. Due to the fact that multiple types of building must be covered, mixed-use structural warranties require tailored terms to cover a range of risk profiles.
Our range of mixed-use policies take varying tenures, shared mechanical or electrical services and more into account to provide the necessary coverage for your needs.
Be aware that insurer underwriting is typically very rigorous, because construction cannot be observed. Insurers are therefore typically more selective over these types of policies.
However, thanks to our wide range of insuring partners, we can help you find the ideal policy for you and your needs.
What percentage of a building has to be commercial to be classed as mixed use?
There is no fixed or minimum percentage that ensures a building is considered ‘mixed-use’ – any combination of commercial and residential premises fall into this category.
However, the structuring of your warranty may vary according to the commercial-residential ratio. Heavily commercial plots with a small residential unit may be covered by a commercial structural warranty, while majority-residential developments might be covered by a home-building warranty, with an additional commercial extension.
Will a mixed-use structural warranty remain valid if the units in the building change?
In most cases, no. Mixed-use warranties are typically issued and underwritten in line with specific business uses and loads, with indemnities according to those factors.
Any major changes, such as converting a residential unit into one for further commercial use, would likely deviate from the original policy’s limit and may void your cover. It’s therefore always recommended that you consult your insurer before converting a unit from its intended purpose.
However, flexible policies may be available in developments with high unit turnover. Contact us to find out more about how we can help.


